Once a quarter, look at your real money — then learn how it grows.
Setup
Open the Spreadsheet
Each quarter you and a parent look at your real money — not play money. That’s how you start learning budgeting and investing: what came in, what went out, and what’s growing.
Open the Numbers app on your Mac or iPad. (It’s the green one with a “+” on a spreadsheet.)
Find the Quarterly Coin spreadsheet. Don’t see it? Ask a parent — they know where it lives.
Open it and click around. You should be able to see it, scroll it, and read the numbers. If it won’t open, stop and get help before you go on.
Lesson 1
Where Does My Money Go?
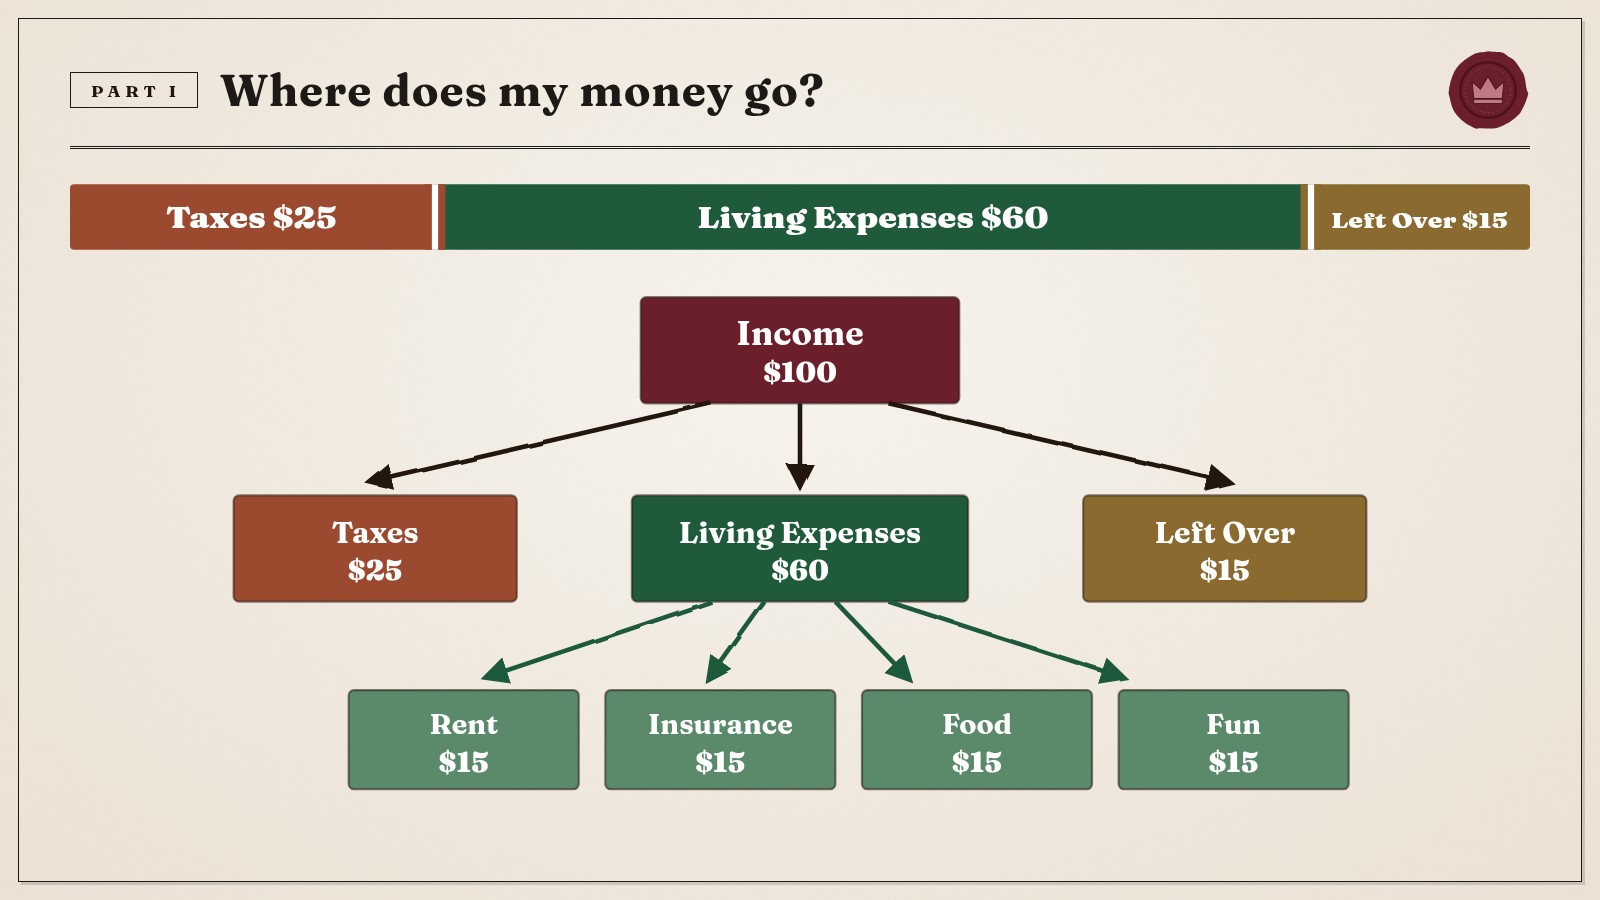
Pretend $100 comes in. That money is your income. It doesn’t all stay in your pocket.
A simple $100 map
Piece
Amount
Income (comes in)
$100
Taxes
$25
Living expenses
$60
Left over
$15
Living expenses ($60) split evenly: Rent $15 · Insurance $15 · Food $15 · Fun $15
Quest scroll: key words for this lesson.
1
Income
Money that comes in, like allowance, gifts, or pay from a job.
2
Expenses
Money you spend on things you need or want, like food, rent, or fun.
3
Net Worth
Everything you own minus everything you owe.
4
Insurance
A small payment now that helps cover big costs if something bad happens later.
5
Mortgage / Loan
Money you borrow now and pay back later, often with a little extra called interest.
6
Rent
Money you pay each month to live in a home you don’t own.
“A personal budget is a financial plan that estimates an individual’s or household’s income and expenses over a defined period, usually a month, to guide spending decisions and promote financial stability.”
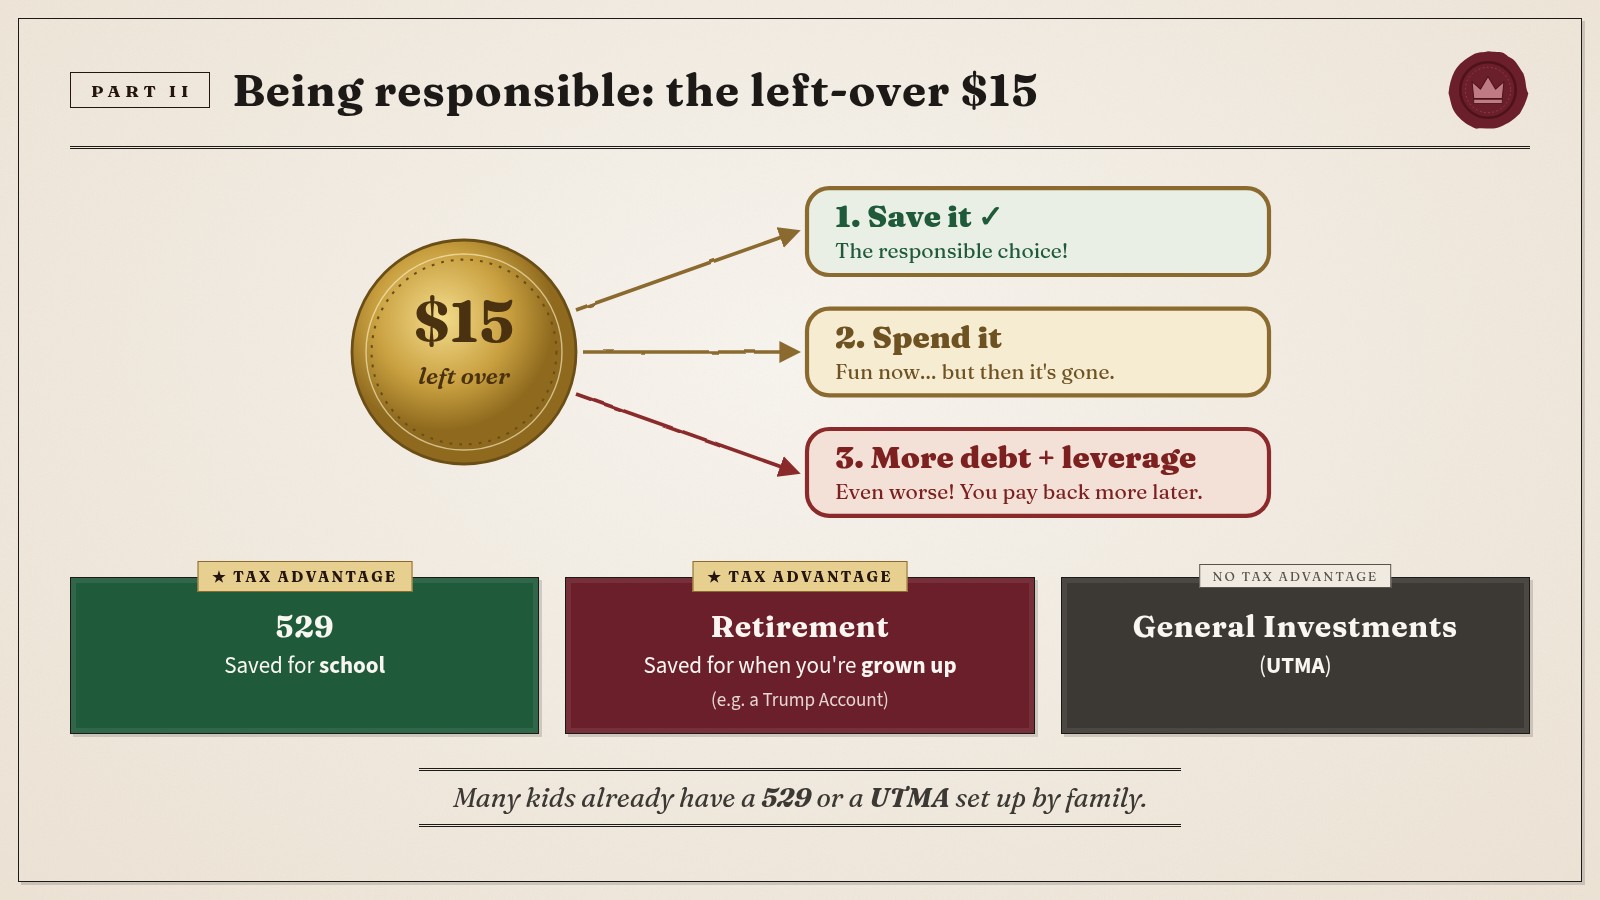
That leftover $15 is a choice. You can save it (the responsible path), spend it, or — worse — take on more debt and leverage it (think of a credit card balance you don’t pay off).
Saving means you can put money into an investment account. Three common types:
529 — saved for school. Often has a tax advantage.
Retirement — saved for when you’re grown up. Often has a tax advantage.
General investments (UTMA) — a custodial account for broader investing. Usually no special tax advantage like the first two.
Quest scroll: key words for this lesson.
1
Tax Advantage
A special rule that lets some savings accounts grow with less tax taken out.
2
Leverage
Borrowing money to make a bigger bet; a credit card is one risky example.
“If you have high interest credit card debt, consider taking steps to pay off that debt aggressively and limit your use of credit cards. If you don’t pay off that balance every month, you’ll be paying interest charges that may greatly exceed the amount you could earn on your savings or investments.”
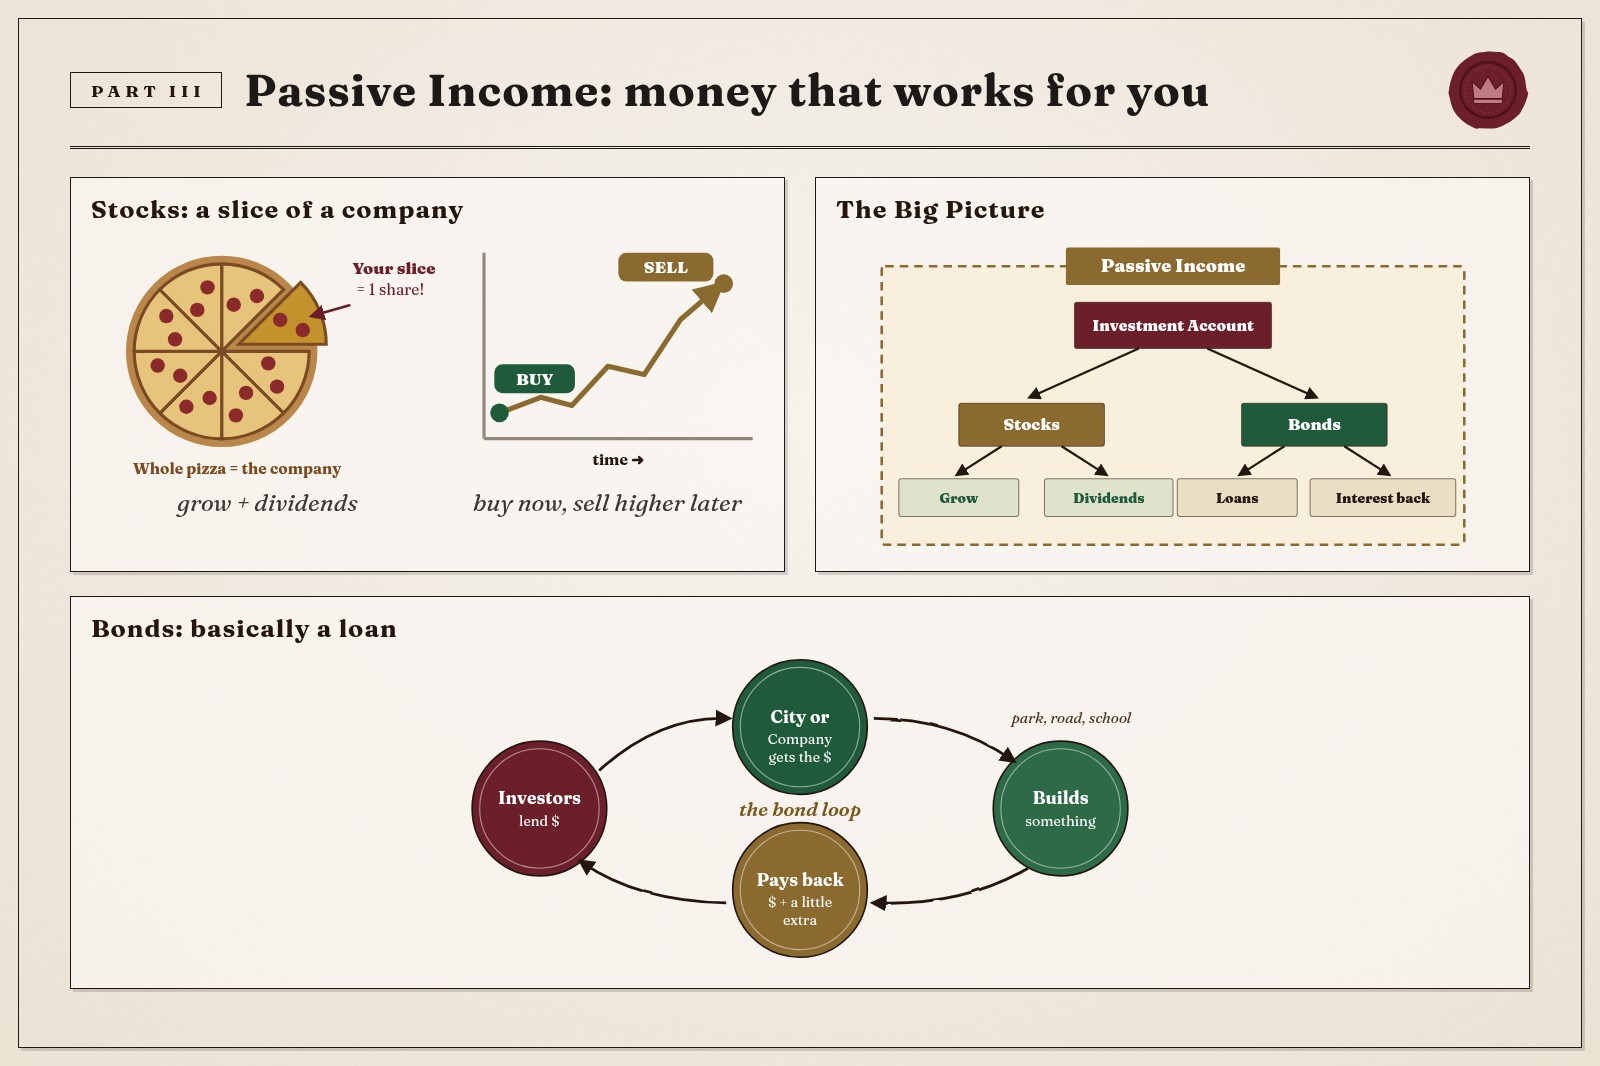
Investment accounts put your money into stocks and bonds. Both can be passive income: your money earns money while you do other things.
Stocks are a slice of a company — they can grow if you buy now and sell higher later, or pay dividends (bonuses to shareholders). Bonds are basically loans: cities and companies borrow to build parks, roads, schools, or factories, then pay back a little extra to the investors. A mortgage works on the same idea.
Quest scroll: key words for this lesson.
1
Stocks
Owning a tiny slice of a company that can grow in value over time.
2
Bonds
A loan you give a government or company, paid back later with a little extra.
3
Dividends
Bonus money a company pays people who own a slice of it.
“That’s what happens when you buy stock in a company — you become one of the owners. … When you buy a bond, you’re lending your money to the company or government that issued it. The bond issuer promises to pay you interest and to return your money on a date in the future.”